Q3 Earnings Season Gains Momentum Amid Market Volatility and Shift Toward AI Infrastructure Stocks

The third-quarter earnings season has commenced against a backdrop of heightened market volatility and a significant recalibration of investor expectations within the technology sector. Following a period of aggressive expansion, the financial markets are currently navigating a complex landscape defined by persistent inflation data, fluctuating interest rate projections, and a critical evaluation of the "AI trade." Last week, the technology-heavy NASDAQ Composite experienced a sharp 4.5% decline, a downturn largely precipitated by a sell-off in semiconductor equities. This retraction highlights growing concerns regarding the sustainability of massive capital expenditures in artificial intelligence (AI) and the potential impact of a "higher-for-longer" interest rate environment on corporate valuations.
The Banking Sector: A Litmus Test for Economic Health
The traditional opening act of the earnings season—the major financial institutions—provided a multifaceted view of the American economy. Reports from giants including Bank of America Corp. (BAC), BlackRock, Inc. (BLK), Citigroup Inc. (C), Goldman Sachs Group, Inc. (GS), JPMorgan Chase & Co. (JPM), Morgan Stanley (MS), and Wells Fargo & Co. (WFC) revealed a divergence in performance and outlook.
JPMorgan Chase and Bank of America both reported results that fell short of analyst projections on both the top and bottom lines. These misses were largely attributed to shifting net interest income (NII) dynamics as the cost of holding deposits rises. Conversely, Citigroup and Morgan Stanley delivered earnings that exceeded consensus estimates, buoyed by robust investment banking fees and trading revenue.
A critical focal point for analysts during these disclosures was credit quality. Wells Fargo, in particular, reported lower-than-anticipated loan-loss provisions. This metric is frequently utilized by economists as a barometer for consumer stability; the lower provisions suggest that despite inflationary pressures, American households and businesses continue to service their debts effectively. While bank earnings are often obscured by complex accounting adjustments, such as changes in reserves and one-time deal-making gains, they remain a vital indicator of the broader economic trajectory and the health of the credit markets.
Chronology of the Q3 Earnings Rollout
The current week marks a pivotal transition from the financial sector to the high-growth technology and consumer discretionary sectors. The following timeline outlines the key reporting windows that are expected to dictate market sentiment in the near term:
- Mid-October Phase: The initial wave focused on global finance and asset management. BlackRock and Goldman Sachs set the stage, highlighting a resurgence in capital markets activity.
- The Technology Pivot: Reporting cycles for Netflix, Inc. (NFLX) and major private entities like SpaceX provide immediate insights into consumer subscription health and the burgeoning space economy infrastructure.
- The "Magnificent Seven" Influence: Mid-week results from Meta Platforms, Inc. (META) and Tesla, Inc. (TSLA) are slated to address the primary themes of 2024: digital advertising recovery, autonomous driving progress, and the sheer scale of AI-related infrastructure investment.
- Storage and Hardware Infrastructure: Late October features results from Western Digital Corporation (WDC) and Seagate Technology Holdings plc (STX). These reports are viewed as secondary indicators of AI demand, as the massive computational power required for AI workloads necessitates a parallel expansion in data storage capacity.
Supporting Data and Analyst Revisions
Despite the recent volatility in the NASDAQ, the fundamental earnings outlook for the S&P 500 remains optimistic. Current data from FactSet indicates that the index is projected to achieve an average earnings growth rate of 29.6% for the third quarter. However, this figure may be conservative. Market analysts have been upwardly revising their estimates as the reporting season nears, a trend that historically signals a high probability of positive earnings surprises.
Historical analysis suggests that when analyst revisions trend positive in the weeks leading up to an announcement, the actual results often exceed the revised consensus. Some market strategists believe that if the current pace of beats continues, the average earnings growth for the S&P 500 could surpass 33% by the conclusion of the season. This potential for "blowout" results serves as a counter-narrative to the fears of a technology bubble, suggesting that the underlying profitability of many firms remains robust.
The Infrastructure Build-Out: Beyond the Chipmakers
While much of the market’s attention has been focused on primary AI chip designers, a broader "infrastructure trade" is beginning to emerge. This includes companies involved in memory, data centers, and power infrastructure. Investor interest is increasingly shifting toward the physical requirements of the digital revolution.
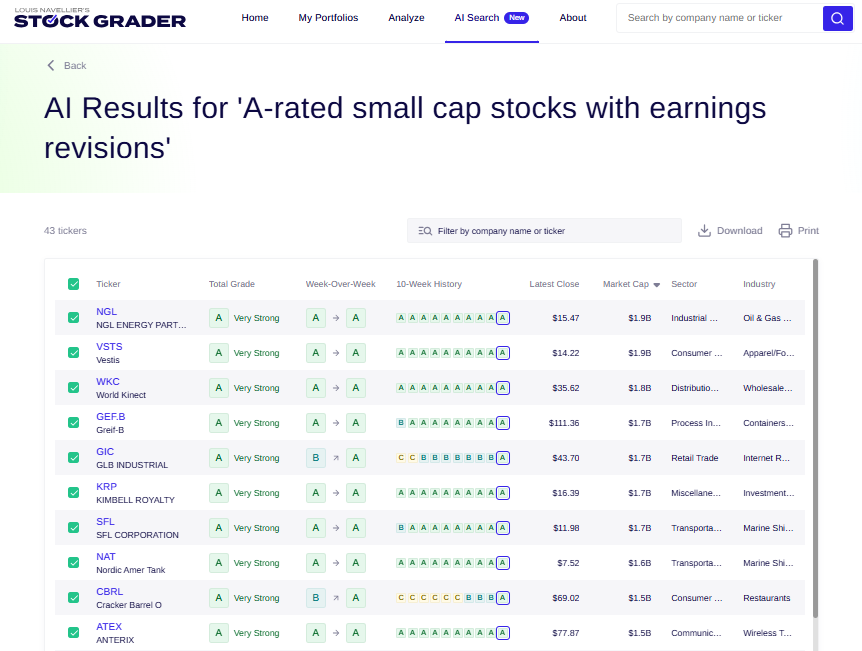
Data storage providers like Western Digital and Seagate are currently benefiting from the "AI tailwind." As AI models become more sophisticated, the volume of data that must be stored and processed grows exponentially. This has led to a stabilization of prices in the NAND and HDD markets, providing a fundamental boost to these companies’ margins. Furthermore, the energy requirements of massive data centers have turned the spotlight on power infrastructure firms. Investors are seeking "A-rated" companies that provide the hardware and electrical components necessary to keep AI servers running. This shift represents a move away from purely speculative AI software plays toward tangible, hardware-based growth.
Official Responses and Market Sentiment
While corporate executives have remained largely optimistic in their prepared remarks, institutional investors have expressed a more cautious "wait-and-see" approach. The primary concern cited by institutional desks is the "Return on Investment" (ROI) for AI. During recent conference calls, analysts have pressed tech CEOs to provide clearer timelines on when the massive capital expenditures in GPUs and data centers will translate into significant revenue growth.
In response, companies like Meta and Google have emphasized that the risk of "under-investing" in AI far outweighs the risk of "over-investing," asserting that the current infrastructure build-out is a generational necessity. This philosophical divide between corporate leadership and skeptical investors is expected to be a recurring theme throughout the October and November reporting cycles.
Broader Impact and Implications for the Q4 Outlook
The results of the Q3 earnings season will likely determine the market’s trajectory for the remainder of the year and into 2025. Several key implications are currently being monitored by market participants:
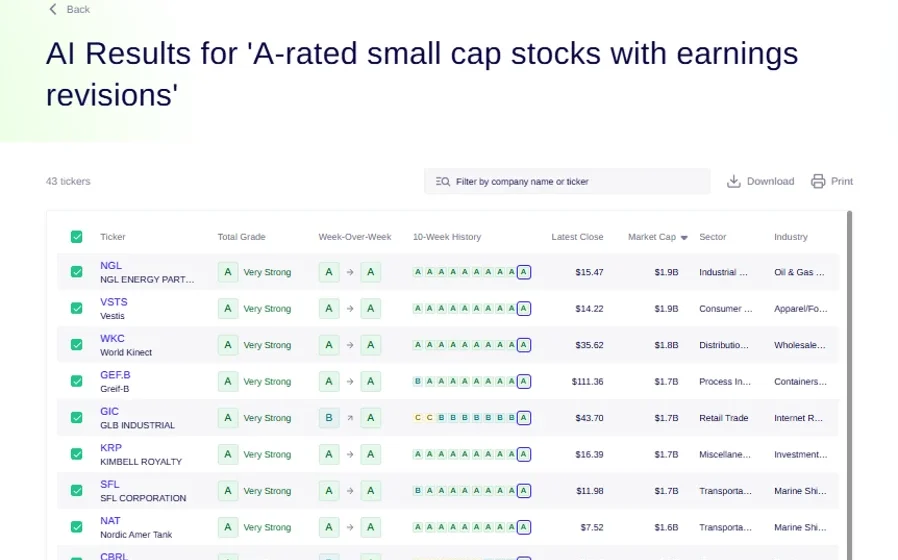
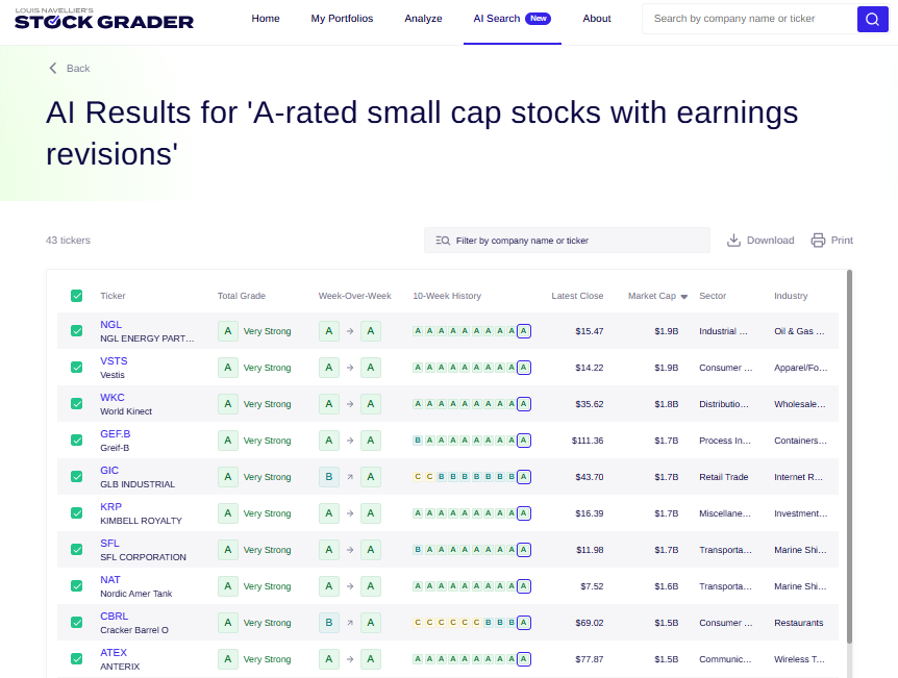
- Small-Cap Resurgence: There is an increasing focus on "A-rated" small-cap stocks. As large-cap technology valuations reach historical highs, capital is beginning to rotate into smaller, fundamentally strong companies that are part of the broader AI and domestic manufacturing supply chains.
- Institutional Accumulation vs. Distribution: A critical metric for the coming weeks will be institutional "Precursor Intelligence." Analysts are closely watching whether "big money" is accumulating shares of tech leaders following the recent dip or if they are quietly exiting positions in favor of defensive sectors.
- Monetary Policy Alignment: If corporate earnings remain strong despite high interest rates, it may provide the Federal Reserve with the leeway to maintain current rates for longer to ensure inflation is fully contained. Conversely, a widespread earnings miss could increase the pressure on the Fed to accelerate rate cuts to prevent an industrial slowdown.
- Earnings Momentum: The concept of "Earnings Momentum"—where companies not only beat expectations but also raise their forward guidance—will be the primary differentiator between stocks that rally and those that stagnate. In a volatile market, investors are increasingly unforgiving of companies that meet current targets but offer cautious or "opaque" future outlooks.
In summary, the third-quarter earnings season is evolving into a critical juncture for the global markets. While the initial banking results provided a mixed view of the consumer landscape, the upcoming reports from the technology and infrastructure sectors will provide the definitive verdict on the health of the AI-driven economy. As analysts revise their growth estimates upward, the potential for significant market movement remains high, provided that the "blowout" earnings expectations can be reconciled with the macroeconomic realities of inflation and interest rate policy. For the discerning investor, the focus has shifted from the "obvious" market leaders to the fundamentally superior candidates that support the underlying architecture of modern industry.