Market Volatility and Policy Shifts Signal New Phase for Artificial Intelligence Infrastructure and Defense Spending

The final trading session of October 2024 concluded with a significant retrenchment in technology equities, marking a volatile period for artificial intelligence (AI) investments as market participants weigh massive capital expenditures against delayed returns. By the close of Friday’s session, the Nasdaq Composite had declined 2.9%, while the S&P 500 and the Dow Jones Industrial Average fell 1.8% and 1%, respectively. The downturn was most pronounced in the semiconductor sector, with the Philadelphia Semiconductor Index (SOX) plunging more than 7% in a single day, capping a month where the index lost more than 15% of its value. This retreat represents the Nasdaq’s most challenging monthly performance since early 2025, reflecting a broader recalibration of expectations surrounding the AI-driven "super-cycle."
Corporate Earnings and the Capital Expenditure Crisis
The primary catalysts for the recent selloff were disappointing quarterly reports and forward-looking guidance from industry titans, specifically Intel Corp. and Amazon.com Inc. Intel experienced its steepest one-day decline on record, with shares falling nearly 29%. The company’s projected fourth-quarter revenue of $15 billion to $16 billion fell significantly short of the $17 billion anticipated by Wall Street analysts. Intel CEO Lip-Bu Tan attributed the shortfall to a slowdown in the personal computer market, compounded by fluctuations in memory pricing and availability. This guidance has renewed concerns regarding Intel’s ability to compete in a landscape increasingly dominated by specialized AI hardware.
Amazon’s financial results presented a more complex narrative. While its cloud computing division, Amazon Web Services (AWS), reported a robust 39% growth rate—reaching $46 billion and suggesting sustained demand for AI infrastructure—the cost of maintaining that growth has become a point of contention. Amazon reported $77.3 billion in capital expenditures for the quarter, more than doubling the $35 billion spent during the same period the previous year. This surge in spending has driven Amazon’s free cash flow more than $42 billion into negative territory over the past 12 months, setting a corporate record.
The "Magnificent Seven" technology stocks, which fueled the market’s rally throughout much of the year, are now facing increased scrutiny. Alphabet Inc. saw nearly $500 billion in market capitalization erased following its latest earnings report, one of the most significant single-day value losses in financial history. Both Alphabet and Meta Platforms Inc. have entered bear market territory, defined as a decline of 20% or more from recent highs. According to estimates from JPMorgan, the leading technology firms are on track to spend approximately $900 billion on AI-related infrastructure this year. The prevailing anxiety among investors is no longer whether AI technology is viable, but rather when the massive upfront investments will yield a proportional return on investment (ROI).
Analytical Perspectives on the AI Investment Lifecycle
Despite the immediate market turbulence, some technology analysts argue that the current selloff is a structural necessity rather than a fundamental failure of the AI trade. Luke Lango, a technology specialist and editor of Early Stage Investor, suggests that the market is currently in a transitional period between investment and monetization. Lango’s analysis of "hyperscaler" earnings indicates that while spending is front-loaded, the payoff remains back-loaded, creating a temporary gap in profitability that has spooked short-term investors.
Lango’s research into the return on AI spending reveals an uneven landscape among the tech giants. Using a cost-of-capital benchmark of approximately 9% to 10%, Microsoft Corp. is currently leading with an estimated 19% return on its AI investments. Alphabet follows with 12%, while Amazon sits at roughly 9% to 10%. Meta Platforms currently lags at an 8% return, reflecting its heavy internal use of AI compute compared to companies that sell compute power as a service.
The backlog of contracted cloud services provides a counter-narrative to the "AI bubble" theory. Microsoft, Amazon, and Google currently hold a combined $1.8 trillion in contracted cloud backlogs. AWS’s growth acceleration for six consecutive quarters suggests that demand remains high, though the risk profile may shift by 2028. Analysts warn that once hyperscaler spending growth eventually slows, suppliers will become increasingly dependent on a broader base of buyers who may be more sensitive to tightening credit conditions.
The Political Landscape: Data Centers on the Ballot
As the United States approaches the midterm elections, the future of AI infrastructure is increasingly being decided at the local level. According to data from Ballotpedia, voters in 10 states are set to decide on at least 41 local measures related to data center development. Ohio has emerged as a primary battleground for this issue, with 21 measures appearing across 18 different communities. These proposals range from complete bans on new construction to strict caps on power consumption.

The shift in public sentiment follows several high-profile rejections of data center projects. Earlier this year, 88% of voters in Monterey Park, California, approved a policy prohibiting data centers, while 90% of voters in Augusta Township, Michigan, rejected a rezoning plan for a similar facility. The primary driver of this opposition is the projected impact on the electrical grid. A 2026 Reuters/Ipsos survey cited by the Brookings Institution found that 77% of Americans are concerned that the massive power requirements of data centers will lead to higher residential electricity rates.
This issue has crossed partisan lines, becoming a central theme in several high-stakes political races. In Ohio’s U.S. Senate race, Democratic incumbent Sherrod Brown has utilized the data center issue in campaign advertisements against Republican challenger Jon Husted. Similar debates are unfolding in the gubernatorial races in Texas and Pennsylvania. In Pennsylvania, Governor Josh Shapiro has already implemented more stringent approval processes for new projects. This growing local resistance threatens to extend the "payback period" for Big Tech’s investments, as slower permitting and rising energy costs complicate the buildout of the national AI infrastructure.
Defense Spending and the Evolution of Autonomous Warfare
Simultaneous with the AI infrastructure debate, a significant shift is occurring in U.S. defense policy and spending. The Pentagon has submitted a $1.5 trillion budget request for fiscal 2027, with $350 billion—nearly a quarter of the total—slated for a budget reconciliation package. This mechanism allows the majority party in Congress to pass spending with a simple majority, bypassing the Senate filibuster. The outcome of tomorrow’s elections will determine whether this reconciliation path remains viable or if the defense budget will face a more contentious appropriations process.
Two primary initiatives dominate the proposed package: the "Golden Dome" missile-defense shield and the Defense Autonomous Warfare Group (DAWG). The DAWG, the Pentagon’s dedicated drone-warfare unit, is requesting $53.6 billion for fiscal 2027. This represents a staggering 240-fold increase from its fiscal 2026 funding of $226 million.
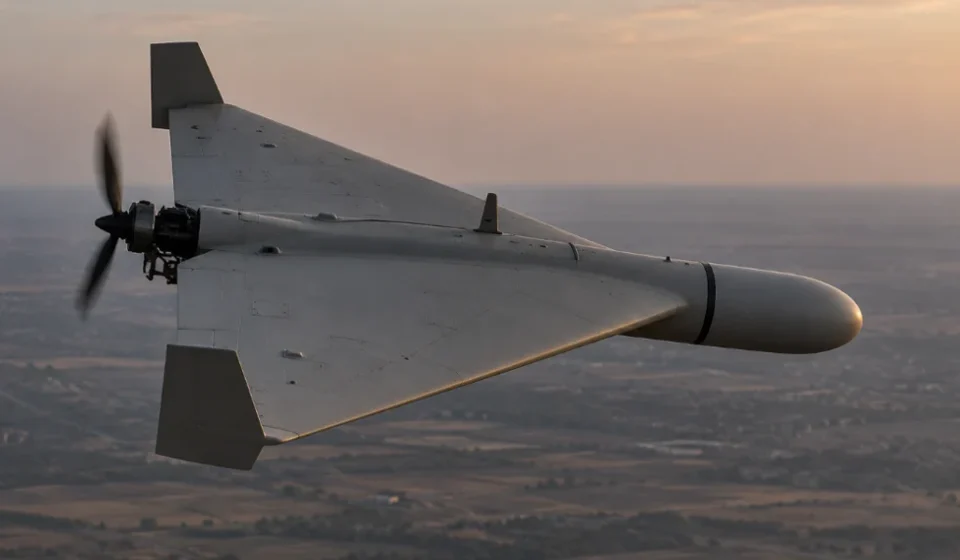
The strategic pivot toward autonomous systems is driven by a stark economic reality in modern warfare: cost asymmetry. During recent conflicts in the Middle East, adversarial forces have utilized Shahed drones, which cost approximately $20,000 to manufacture, in large-scale swarms. In contrast, the U.S. Patriot interceptor missiles used to neutralize these drones cost between $3 million and $4 million per unit. This "Ferrari vs. Civic" economic disparity is unsustainable in long-term conflicts, prompting the Pentagon to accelerate the development of cheap, mass-produced autonomous systems.
The Industrial Base and the "Pennsylvania Plan"
The rearmament of the United States is expected to involve a deep integration of public and private sectors. Since July, the Pentagon has entered into multiyear contracts valued at over $100 billion to replenish missile stockpiles. However, industry leaders have noted that until Congress formally appropriates the funds, contractors are limited in their ability to expand manufacturing capacity.
This bottleneck has led to the emergence of initiatives like the "Pennsylvania Plan," a strategic framework discussed at a recent summit organized by Senator Dave McCormick. The plan brings together Wall Street financiers, defense officials, and emerging technology firms to revitalize the American defense industrial base. Analysts suggest that this public-private partnership will likely proceed regardless of the specific outcome of the reconciliation package, as the shift toward low-cost autonomous weapons is increasingly viewed as a national security imperative.
Implications for the Near-Term Market Outlook
The convergence of market volatility, local political resistance to infrastructure, and a shifting defense landscape suggests that the coming months will be a period of significant realignment. For investors in the AI space, the upcoming election serves as a referendum on the public’s patience for the physical buildout of the digital economy. For the defense sector, it will determine the velocity of a multi-billion-dollar transition toward autonomous warfare.
While the "meltdown week" for AI stocks has caused immediate financial pain, the underlying data suggests a sector that is maturing rather than collapsing. The transition from pure speculation to a focus on ROI and physical infrastructure limits indicates that the next phase of the AI trade will be defined by operational efficiency and political navigation rather than just raw compute power. As the market moves past the "noisy" quarterly results of late 2024, the focus will shift to how these technological and political developments translate into long-term fiscal policy and corporate strategy.