Contradictory Market Signals Drive Investor Interest Toward Energy and AI Infrastructure Amid Federal Reserve Uncertainty

The financial landscape in October has been defined by a series of deep economic contradictions, as traditional market indicators diverge from sector-specific performance. While macroeconomic data—particularly regarding inflation and interest rates—has signaled potential volatility, specific segments of the market, including artificial intelligence (AI) infrastructure and the energy sector, continue to report robust fundamental growth. As the Federal Open Market Committee (FOMC) convenes for its October meeting, investors are grappling with a market environment where high inflation and elevated interest rates coexist with record-breaking earnings in select industries.
The Macroeconomic Paradox: Inflation vs. Treasury Yields
The primary source of market tension throughout the month has been the disconnect between inflation data and the bond market. September’s Consumer Price Index (CPI) reports were widely characterized by analysts as disappointing, showing persistent price pressures that initially ignited fears of further hawkishness from the Federal Reserve. Under normal market conditions, "horrific" inflation data would be expected to drive Treasury yields higher as investors price in more aggressive rate hikes.
However, the 10-year Treasury yield followed an unexpected trajectory. After peaking at 5.3% on October 5, the yield began a steady decline, falling to just below 5% by the final week of the month. This inversion of expectations suggests a "flight to safety" or a growing belief among bond traders that the economy may be cooling sufficiently to prevent further escalation.
The FOMC meeting, scheduled for the final days of October, serves as a critical pivot point for this narrative. While the consensus among economists is that the Fed will hold interest rates steady in the current 5.25% to 5.50% range, the accompanying FOMC statement and Chair Jerome Powell’s subsequent press conference are expected to provide clarity on the "higher for longer" policy stance. Market participants are looking for signals on whether the recent decline in yields will persist or if the Fed’s commitment to reaching its 2% inflation target will necessitate a year-end rate hike.
The AI Growth Divergence: Earnings vs. Market Punishment
The second major contradiction is found within the technology sector, specifically concerning companies involved in the artificial intelligence and data center buildout. According to recent quarterly data, the Information Technology sector is projected to post earnings growth of 65.6%, the second-highest growth rate of any sector this quarter. This surge is driven by the massive capital expenditures of "hyperscalers"—large cloud providers—and the hardware manufacturers that supply them.
Despite these phenomenal sales and earnings figures, AI-related stocks have faced significant downward pressure. Market analysts attribute this "punishment" to growing concerns over financing. As interest rates remain elevated, the cost of funding the massive infrastructure projects required for AI—including specialized chips, liquid-cooled data centers, and high-capacity power grids—has become a point of contention for investors. There is a palpable fear that the capital-intensive nature of AI will erode long-term margins, leading to what some describe as "throwing the baby out with the bathwater," where fundamentally strong companies are sold off alongside more speculative ventures.
The Resurgence of the Energy Sector
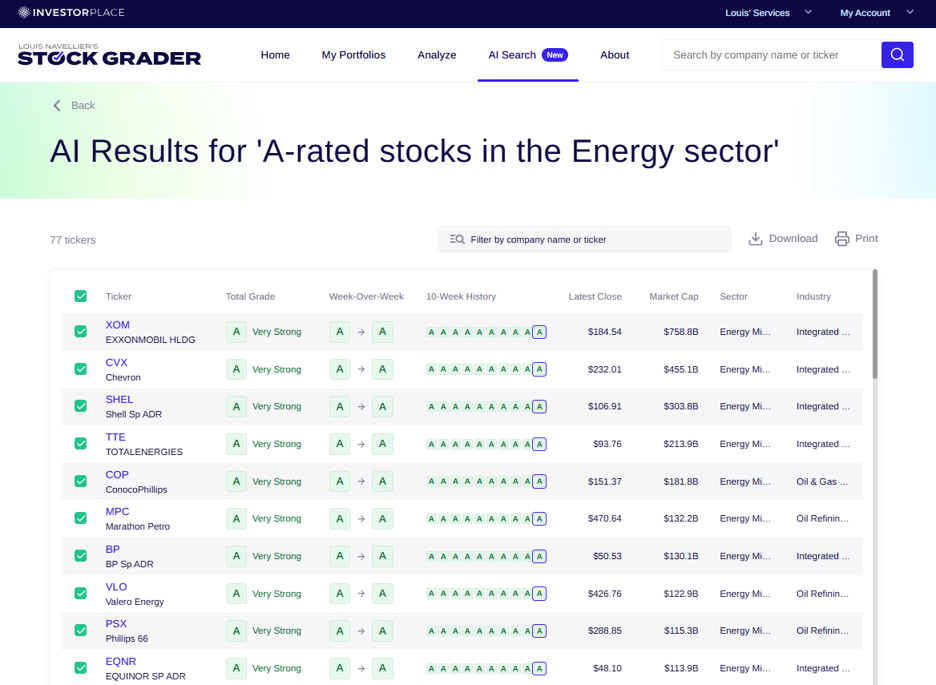
Amid the volatility in tech and bonds, the energy sector has emerged as a bastion of relative strength. This resurgence is fueled by a combination of geopolitical instability and a tightening of global supply-demand dynamics.
Recent reports from the Persian Gulf indicate that while crude oil shipments through the Strait of Hormuz have topped 24 million barrels per day—surpassing pre-war levels—global prices remain stubbornly high. Brent crude oil is currently trading near $115 per barrel, while West Texas Intermediate (WTI) holds at approximately $101 per barrel. These elevated prices are largely attributed to regional instability and repeated attacks on oil infrastructure in Saudi Arabia, which have kept a "risk premium" baked into the price of every barrel.
For the corporate energy sector, these high prices have translated into a massive windfall. FactSet data indicates that the energy sector is expected to post average earnings growth of 127.6% for the third quarter. This is a significant upward revision from estimates provided just weeks ago, which sat at 114.8%. The sector’s ability to generate cash flow in a high-rate environment has made it a primary target for investors seeking "defensive growth."
Consumer Impact and the Cost of Energy
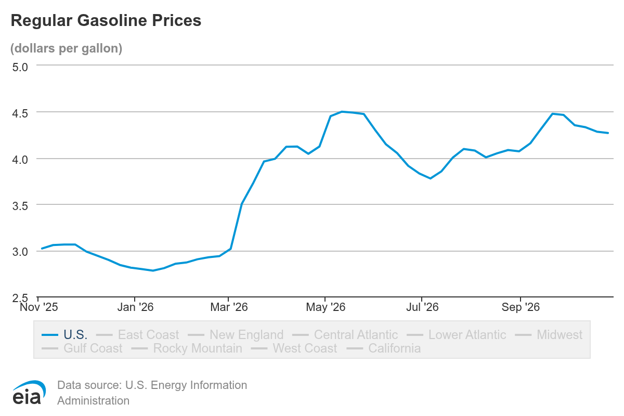
While energy companies and their shareholders are benefiting from the current environment, the broader American public is feeling the "pinch at the pump." Data from the Energy Information Administration (EIA) paints a stark picture of the inflationary pressure on consumers:
- Gasoline: The average price for a gallon of gasoline in the U.S. has reached $4.28. This represents a more than 40% increase compared to October of the previous year.
- Diesel: The situation is even more acute in the logistics and transport sector, where diesel prices have surged more than 70% year-over-year to $6.28 per gallon.
These fuel costs act as a "stealth tax" on the economy, increasing the cost of transporting goods and contributing to the "sticky" inflation that the Federal Reserve is currently battling. The high cost of diesel is particularly concerning for economists, as it directly correlates with the price of food and consumer staples delivered by truck and rail.
Investor Sentiment and Search Trends
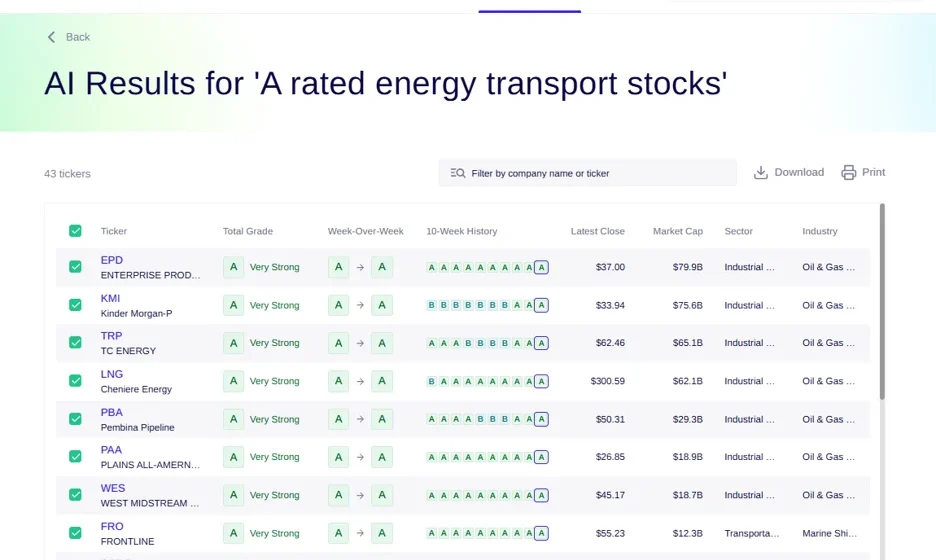
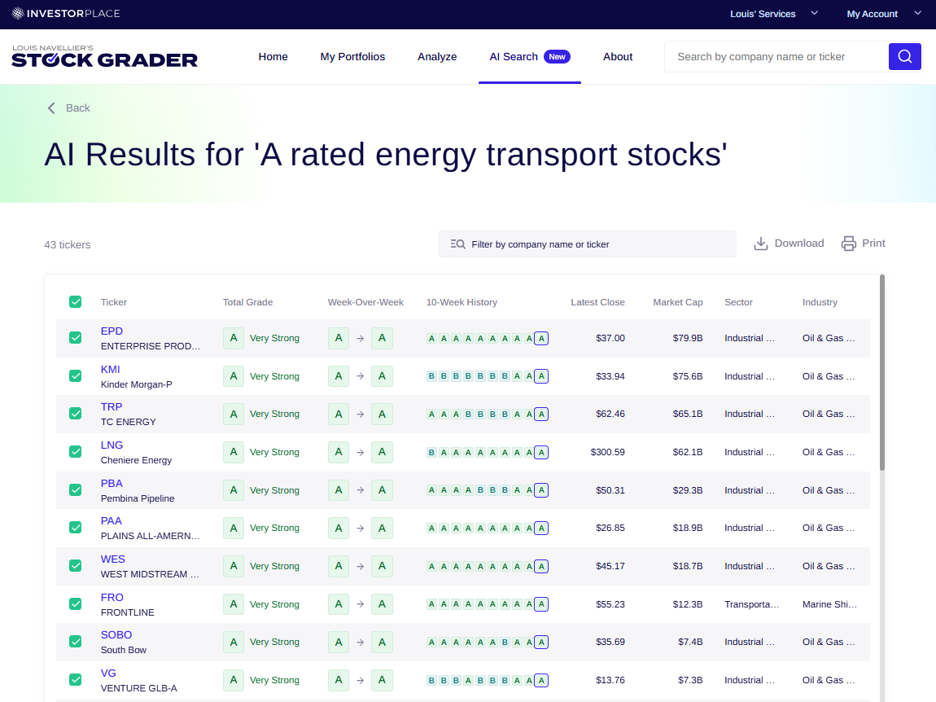
Data from proprietary AI-driven stock analysis tools reveals a significant shift in retail and institutional investor behavior during the week of October 19. An analysis of over 9,000 search prompts indicates that investors are moving away from speculative "moonshot" stocks and toward "A-rated" fundamental opportunities.
The most popular search categories included:
- A-Rated Stocks: 362 searches for top-tier fundamental ratings across all sectors.
- Small-Cap Opportunities: 333 searches for A-rated small-cap companies, suggesting a hunt for undervalued gems that may have been overlooked during the large-cap tech rally.
- AI Infrastructure: 295 searches specifically for companies building the "backbone" of AI (data centers, power management, and cooling) rather than just software applications.
- Energy Minerals: 118 searches specifically mentioning energy, with a focus on companies involved in extraction, transport, and processing.
This data suggests that the "smart money" is currently focused on sectors with tangible assets and clear earnings visibility, rather than purely speculative growth.
Chronology of Key October Market Events
To understand the current market posture, one must look at the sequence of events that shaped the month:
- October 5: The 10-year Treasury yield hits a multi-year peak of 5.3%, causing a broad market sell-off.
- October 12: September inflation data is released, showing higher-than-expected price increases, particularly in the services sector.
- October 19: Peak investor activity in search tools shows a pivot toward energy and AI infrastructure as earnings season begins.
- October 24: Reports confirm Persian Gulf exports have recovered to 24 million barrels per day, yet prices remain high due to geopolitical risk.
- October 30-31: The FOMC meeting begins, with the market pricing in a 98% chance of a rate pause but focused entirely on future guidance.
The $31.5 Trillion Transformation: Long-term Implications
Looking beyond the immediate volatility of October, market analysts are pointing toward a massive structural shift in the American economy. Some estimates suggest that the ongoing energy transformation—encompassing the expansion of domestic oil and gas production alongside the transition to modern infrastructure—could be worth upwards of $31.5 trillion over the next 15 years.
This expansion is not limited to "drilling" alone. It encompasses a massive buildout of midstream and downstream assets:
- Pipelines: The need for high-capacity pipelines to move natural gas to export terminals.
- Export Terminals: The expansion of Liquefied Natural Gas (LNG) facilities to meet European and Asian demand.
- Processing Facilities: Modernizing refineries to handle different grades of crude and improving efficiency.
This "Energy Expansion" is increasingly being viewed as a parallel to the "AI Buildout." Both require massive amounts of capital, both are essential for national security and economic competitiveness, and both are currently being led by companies with superior fundamental ratings.
Conclusion: Navigating the Contradictions
The market at the end of October remains a complex puzzle. On one hand, the Federal Reserve’s battle with inflation creates a ceiling for market valuations. On the other hand, the sheer earnings power of the energy and technology sectors provides a floor.
For investors, the takeaway from this "month of contradictions" is the importance of fundamental superiority. As the 127.6% earnings growth in energy and the 65.6% growth in tech suggest, the companies that are actually delivering results are the ones most likely to weather the macroeconomic storm. While the "baby has been thrown out with the bathwater" in some sectors due to financing fears, the eventual stabilization of Treasury yields and a clearer path from the FOMC may provide the catalyst for these fundamentally strong stocks to decouple from the broader market’s malaise.