Market Regime Change Accelerates as Capital Rotates from Big Tech Toward Industrial Commodities and AI-Integrated Mining Operations

The global financial markets are currently undergoing a fundamental reorganization, a phenomenon often referred to as a "regime change," where investment capital pivots from high-growth technology sectors into tangible, asset-backed industries. This shift mirrors historical patterns observed during previous technological revolutions, most notably the transition seen during the early 2000s following the collapse of the dot-com bubble. As the initial fervor surrounding generative artificial intelligence (AI) begins to mature, investors are increasingly scrutinizing the sustainability of the "Magnificent Seven" stocks—Alphabet Inc., Amazon.com Inc., Apple Inc., Meta Platforms Inc., Microsoft Corp., Nvidia Corp., and Tesla Inc.—and are instead seeking opportunities in sectors that provide the physical infrastructure and raw materials necessary for the next phase of global industrialization.
The Historical Precedent of Market Cycles
To understand the current rotation, one must examine the cyclical nature of innovation and capital allocation. Historically, new technology cycles follow a predictable four-stage progression: the emergence of a groundbreaking innovation, the manifestation of a critical bottleneck, a massive influx of capital to resolve that bottleneck, and finally, a total regime change in market leadership.
During the late 1990s, the innovation was the commercial internet. The subsequent bottleneck was the lack of bandwidth and hardware infrastructure. While capital initially flooded into "pure-play" internet companies, the eventual market correction in 2000 saw a drastic reorganization. High-profile names like Amazon, Intel, and Cisco saw their valuations plummet by 80% or more. Simultaneously, capital rotated into "real-world" sectors. Between 2000 and 2005, while the tech-heavy Nasdaq struggled to recover, sectors such as base metals, precious metals, energy, and utilities delivered consistent double-digit and triple-digit returns. This historical backdrop serves as a roadmap for the current market environment, where the initial AI hype is giving way to the logistical and material realities of implementation.
The Magnificent Seven and the Emerging Tech Bottleneck
Since the debut of sophisticated large language models (LLMs) in late 2022, the Magnificent Seven have dominated market indices, accounting for a disproportionate share of the S&P 500’s gains. However, market analysts have begun to identify a "bottleneck phase" in the AI revolution. The primary constraints are no longer just software-based; they are physical. The massive energy requirements of data centers, the scarcity of high-performance GPUs, and the surging demand for conductive metals like copper have created a ceiling for pure-play software growth.
This bottleneck is prompting a rotation out of "high-beta" tech stocks—those that are highly sensitive to market volatility—and into asset-heavy sectors. Investors are increasingly favoring companies with "moats" built on physical assets, such as land, mineral rights, and proprietary industrial processes. This transition is not an abandonment of AI, but rather a shift toward "Applied AI," where the technology is used to enhance the efficiency of traditional industries.
Chronology of Recent Market Developments
The shift in investor sentiment has been punctuated by several key events in the third quarter of 2026:
- September 16, 2026: Concerns regarding the pace of AI development surfaced following the resignation of key researchers at Anthropic. Industry leaders, including Dario Amodei, Sam Altman, and Elon Musk, have publicly discussed the necessity of pacing AI development to ensure safety and alignment. This has led investors to look toward the "application layer" of AI, particularly in robotics and food-service automation, rather than just foundational models.
- September 17, 2026: Market volatility increased as Anthropic sought a $2 trillion valuation for its impending IPO. The massive valuation gap between private expectations and public market realities highlighted the uncertainty in predicting which AI firms will ultimately achieve profitability.
- September 19, 2026: Analysts began sounding the alarm on the "commoditization" of AI. Much like the Spokane gas station price wars, where identical products led to a "race to the bottom" in pricing, the proliferation of GPU-rental "neoclouds" and interchangeable AI models has started to squeeze profit margins.
- September 20, 2026: The All-In Summit, featuring industry titans like Satya Nadella and Jensen Huang, underscored a continued commitment to AI infrastructure. However, the focus shifted toward physical integration, such as Agility Robotics’ "Digit 5" humanoid robot, which is designed for industrial safety and repetitive logistics tasks.
The Strategic Importance of Copper and Freeport-McMoRan
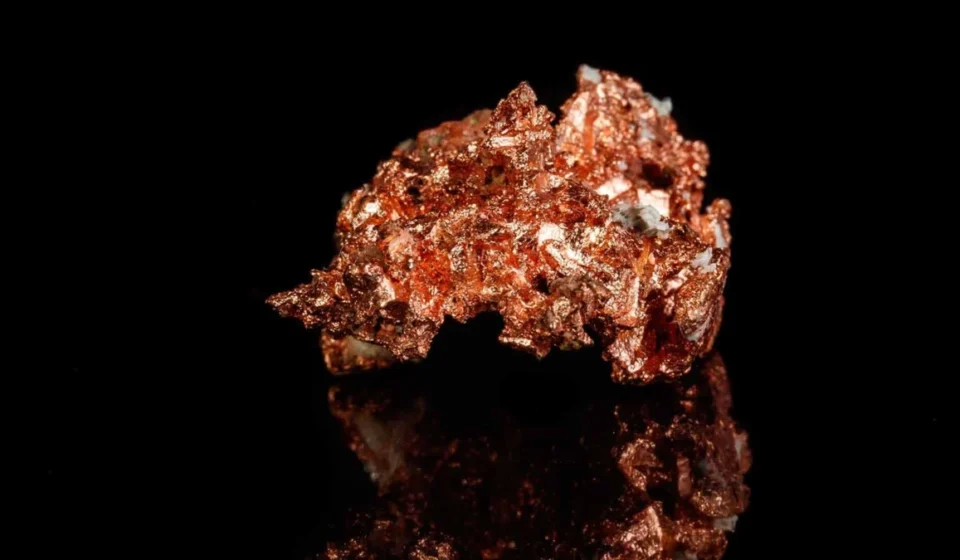
As the market rotates toward tangible assets, copper has emerged as a critical "AI survivor" commodity. Copper is indispensable for the high-density power applications required by AI data centers, as well as the broader global transition toward electric vehicles and renewable energy grids. Freeport-McMoRan Inc. (FCX), one of the world’s largest publicly traded copper producers, stands at the intersection of traditional mining and advanced technology.
Freeport-McMoRan has effectively utilized AI to solve the "production bottleneck" in the mining industry. Mining is an inherently capital-intensive and operationally complex endeavor where even minor efficiency gains can result in hundreds of millions of dollars in additional revenue. The company has implemented several AI-driven initiatives to maximize output:
- Advanced Leaching Techniques: FCX has developed proprietary methods to extract commercial quantities of copper from waste rock that was previously considered uneconomical. By using AI to monitor and optimize the chemical balance in leaching piles, the company can recover "hidden" copper without the need for new, large-scale excavations.
- Ore Sequencing and Throughput: Using machine learning algorithms, Freeport optimizes the sequencing of ore processing. The AI analyzes geological data to determine which rock should be moved first and at what speed it should pass through the mills to maximize recovery rates.
- Predictive Maintenance: AI sensors on heavy machinery allow the company to predict equipment failure before it occurs, significantly reducing downtime in remote mining locations.
- Geological Modeling: Machine learning is applied to vast datasets of historical drilling and satellite imagery to improve the accuracy of reserve estimates and guide long-term mine planning.
This approach represents "applied intelligence" in its most profitable form: increasing the yield of an existing ore body while lowering the per-pound cost of production. As Big Tech faces valuation headwinds, asset-heavy companies like Freeport are increasingly viewed as the more stable "throne" for long-term capital.
Data Analysis: The Rise of Real-World Assets
Current market data supports the thesis of a rotation. While the tech sector’s price-to-earnings (P/E) ratios remain at historical highs, industrial and mining sectors are trading at more conservative valuations despite rising demand for their outputs. For instance, the demand for copper is projected to double by 2035 to meet net-zero and AI infrastructure goals, yet the global pipeline for new copper mines remains thin due to the 10-to-15-year lead time required to bring a new mine online.
This supply-demand imbalance provides companies with "real pricing power"—the ability to maintain margins even in an inflationary or volatile environment. In contrast, "neocloud" providers and software firms without proprietary data moats are seeing their pricing power eroded by intense competition and the rapid obsolescence of early-generation AI models.
Official Responses and Industrial Sentiment
Industry leaders in the industrial sector have expressed cautious optimism about this shift. During recent earnings calls, executives at major mining and utility firms have noted that the "AI tax"—the increased cost of energy and materials driven by tech expansion—is actually a boon for their bottom lines.
"We are no longer just a mining company; we are a technology-enabled resource provider," stated one industry executive during the All-In Summit. "The same AI that the tech world uses to generate images, we use to ensure that every ton of rock we move is optimized for the global supply chain."
Furthermore, government officials have begun to recognize the national security implications of this regime change. The push for "reshoring" industrial capacity and securing domestic supplies of critical minerals like copper and lithium has led to new subsidies and streamlined permitting processes for asset-heavy companies operating within the United States and allied nations.
Broader Impact and Market Implications
The ongoing regime change suggests a move toward a more "barbell" investment strategy. On one end, investors are maintaining exposure to the few AI winners that possess genuine pricing power and proprietary hardware. On the other end, there is a massive surge in "real-world" allocations—commodities, energy infrastructure, and automated manufacturing.
The implications for the Magnificent Seven are significant. While they are unlikely to disappear, their period of unchallenged dominance may be ending as they transition from "growth" stocks to "utility" stocks. As the "innovation" phase of AI transitions into the "infrastructure" phase, the companies that own the dirt, the copper, and the power plants are poised to capture the next wave of profits.
In conclusion, the market is signaling a return to fundamentals. The innovation of AI has reached the stage where it must be integrated into the physical world to continue its expansion. This shift favors "asset-heavy" companies that can leverage AI to enhance tangible production. As history shown in the post-2000 era, those who recognize the regime change early and rotate into resource-backed sectors are often the ones who survive and thrive through the subsequent market cycle.