The Evolution of Artificial Intelligence Investment From Infrastructure to Application and the Historical Parallels of Economic Transformation

In the summer of 1919, then-Lieutenant Colonel Dwight D. Eisenhower participated in a military operation that would eventually redefine the American landscape and its economic engine. As part of the Transcontinental Motor Convoy, Eisenhower and a team of 280 personnel set out from Washington, D.C., to San Francisco. While a modern traveler can complete this 3,000-mile journey in approximately 45 hours of driving time across well-maintained interstates, the 1919 expedition was a grueling 56-day ordeal. The convoy, consisting of 81 motorized vehicles, faced a harrowing reality: the American interior lacked a cohesive road network. Reports from the journey indicated that nearly all roadways from Illinois through Nevada were unpaved, consisting of dirt, sand, and quicksand. The military personnel were forced to repair or rebuild dozens of wooden bridges that buckled under the weight of the trucks, and vehicles frequently became mired in mud, requiring manual extraction.
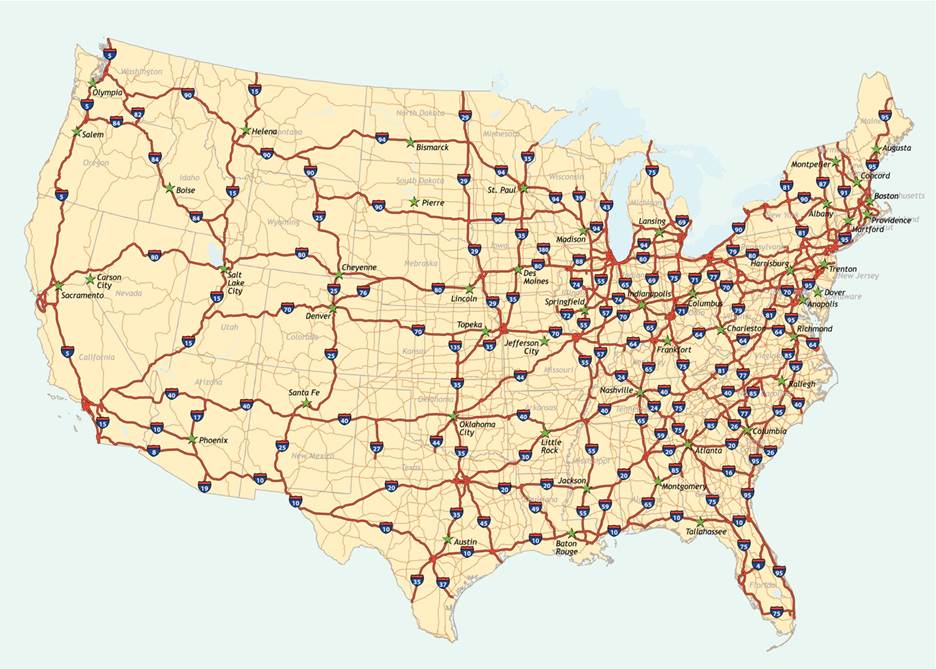
This arduous experience left an indelible mark on Eisenhower. Decades later, as the 34th President of the United States, he leveraged these memories to champion the Federal-Aid Highway Act of 1956. This landmark legislation authorized the construction of the Interstate Highway System, an infrastructure project that would become the largest public works program in human history at the time. The transition from the "convoy era" of 1919 to the "interstate era" of the late 1950s serves as a profound historical parallel to the current trajectory of the artificial intelligence (AI) sector. Just as the construction of physical roads created a foundation for secondary industries to flourish, the current multibillion-dollar buildout of AI data centers and semiconductor networks is setting the stage for a new generation of economic beneficiaries.
The Economic Multiplier of Infrastructure Buildouts
The Federal-Aid Highway Act of 1956 was initially authorized with a budget of $25 billion, but its long-term economic impact far exceeded the initial investment. According to data from the American Society of Civil Engineers (ASCE), the Interstate Highway System has generated more than $6 in economic activity for every $1 spent on construction. However, a critical observation for market analysts is that the primary wealth generated by this system did not remain with the construction firms that laid the asphalt. Instead, the most significant and sustained profits were captured by companies that utilized the infrastructure to revolutionize their business models.
The ease of travel and the speed of logistics birthed global giants in the shipping and retail sectors. Corporations such as FedEx and United Parcel Service (UPS) transformed from local or regional players into international logistics powerhouses by capitalizing on the reliability of the interstate network. Similarly, the hospitality and food service industries underwent a radical shift. The "highway economy" enabled the rise of franchised brands like McDonald’s, Waffle House, and Cracker Barrel, which relied on the predictable flow of interstate traffic. Hotel chains such as Motel 6 and Holiday Inn strategically positioned their assets at highway interchanges, creating a standardized experience for a newly mobile American public. None of these companies built the roads, yet they became the primary beneficiaries of the infrastructure’s existence.
The Current State of Artificial Intelligence Infrastructure
In the contemporary landscape, a similar "buildout phase" is occurring within the digital realm. Major technology conglomerates, often referred to as "Hyperscalers," are engaged in a massive capital expenditure (Capex) cycle to establish the physical foundation for artificial intelligence. Microsoft, Amazon, Alphabet, and Meta Platforms have collectively committed hundreds of billions of dollars to the procurement of high-end semiconductor chips, the construction of massive data centers, and the acquisition of energy resources to power these facilities.
Market data indicates that in 2023 and 2024, the demand for AI infrastructure reached unprecedented levels. NVIDIA, the primary provider of the graphics processing units (GPUs) essential for training large language models, saw its market capitalization soar as it became the "paving company" of the AI era. Wall Street has largely focused its attention on these infrastructure providers, rewarding the companies that manufacture the hardware and manage the cloud environments. However, historical precedents suggest that the market may be approaching a "Separation Phase," where the focus shifts from those building the technology to those applying it effectively.
Chronology of Market Cycles: From Dot-Com to AI
The current AI boom mirrors the evolution of the internet in the late 1990s and early 2000s. During that period, investors poured capital into telecommunications firms and hardware manufacturers. Companies like Cisco Systems and Corning were the darlings of the market, as they laid millions of miles of fiber-optic cable and manufactured the routers that powered the early web. At its peak in March 2000, Cisco was the most valuable company in the world, trading at over 100 times its earnings.
However, as the infrastructure reached a point of saturation and the cost of bandwidth began to plummet, the value proposition shifted. While Cisco’s stock eventually collapsed by nearly 90% during the dot-com bust, a different class of winners emerged: the "Appliers." These were companies that didn’t necessarily build the internet but used its connectivity to transform legacy industries.
A notable example from this era is Humana, the health insurance provider. In the early 2000s, while the market was obsessed with fiber-optics, Humana was quietly integrating internet-based systems to streamline claims processing, reduce administrative overhead, and enhance data analytics for patient care. While technology-heavy indices were crashing, Humana’s stock began a long-term ascent, gaining more than 350% over the five years following the crash and eventually seeing gains of roughly 4,000% over the subsequent two decades. This pattern highlights a recurring theme in economic history: the greatest long-term value often resides in the application of a general-purpose technology rather than the technology itself.
Defining the AI Applier: The Separation Phase
Market analysts are now identifying what is termed the "Separation Phase" in the AI cycle. This phase occurs when the initial excitement over hardware and infrastructure begins to wane, and the market starts to differentiate between companies that are merely spending on AI and those that are generating a return on investment (ROI) from it. These "AI Appliers" are often found in traditional sectors such as healthcare, finance, logistics, and manufacturing.
The characteristics of a successful AI Applier include:
- Operational Efficiency: Using AI to automate complex workflows and reduce labor costs.
- Proprietary Data Utilization: Leveraging existing datasets to train niche models that provide a competitive advantage.
- Customer Experience Enhancement: Implementing AI to provide personalized services at a scale previously impossible.
- Predictive Analytics: Utilizing machine learning to forecast market trends, supply chain disruptions, or consumer behavior.
For instance, in the logistics sector, companies are using AI to optimize routing in real-time, significantly reducing fuel consumption and delivery times beyond what was possible with standard GPS. In the pharmaceutical industry, AI is being applied to protein folding and drug discovery, potentially shortening the timeline for new treatments from decades to years.
Analysis of Implications and Market Outlook
The shift toward AI application has significant implications for global productivity. A report by PwC estimates that AI could contribute up to $15.7 trillion to the global economy by 2030, with the majority of that impact coming from increased labor productivity and product enhancements. As the "cost of intelligence" drops—much like the cost of bandwidth dropped in the 2000s—the barrier to entry for AI integration will lower, allowing mid-sized and large-cap legacy firms to see margin expansions.
However, this transition also presents risks for investors who remain overly concentrated in infrastructure. If the "Hyperscalers" do not see a corresponding rise in revenue from their massive Capex investments, a market correction in the hardware sector is possible. Consequently, the consensus among macro investors is shifting toward identifying "overlooked" companies—firms that may not have "AI" in their name but have integrated the technology so deeply into their operations that they are poised to disrupt their respective industries.
As the political and economic landscape evolves, particularly following major electoral cycles which often bring changes to tax and regulatory policies, the environment for these AI Appliers may become even more favorable. The focus on domestic manufacturing and infrastructure efficiency typically aligns with the capabilities offered by advanced AI integration.
Conclusion: The Long-Term Trajectory
The journey from Eisenhower’s mud-clogged convoy in 1919 to the high-speed transit of the 21st century demonstrates that infrastructure is merely the prologue to economic transformation. The Interstate Highway System did more than just move cars; it reshaped where Americans lived, how they shopped, and how businesses operated.
Artificial intelligence is currently in its "1956 moment." The roads are being built, the "asphalt" of data centers is being laid, and the "bridges" of high-speed chips are being set in place. While the builders have enjoyed the first wave of prosperity, the lessons of history suggest that the most enduring fortunes will be made by those who navigate these new digital highways to deliver goods, services, and innovations in ways that were previously unimaginable. The transition from the infrastructure phase to the application phase is not merely a market trend; it is the next step in the ongoing evolution of the modern economy.