The Strategic Evolution of Industrial Demand Shocks From World War II Aluminum to the Artificial Intelligence Era of 2027

The global economic landscape is frequently defined by "demand shocks," rare periods where the necessity for a specific commodity or technology accelerates at a pace that far outstrips existing manufacturing capacity. Historically, these shocks have served as the primary catalysts for massive industrial expansion and radical shifts in market leadership. As the global economy moves toward 2027, financial analysts and industrial historians are drawing striking parallels between the mobilization of the American aluminum industry during the 1940s and the current explosive demand for high-performance semiconductor technology driven by artificial intelligence.
The Historical Precedent: The Aluminum Crisis of 1940
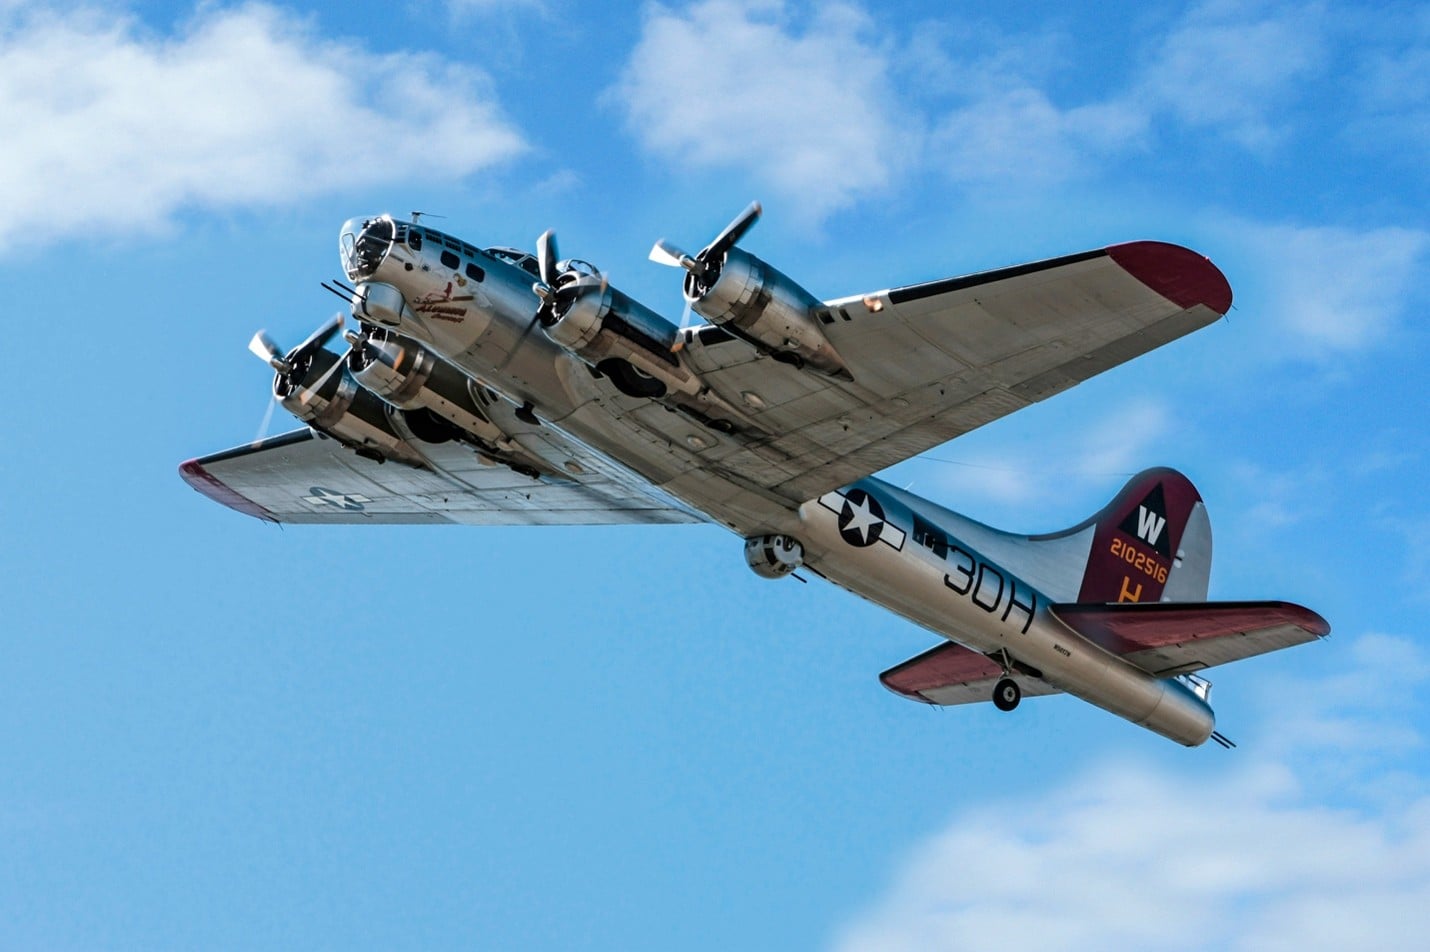
In 1940, as the conflict in Europe escalated, the United States military leadership identified a critical vulnerability in national defense: the lack of adequate materials for air superiority. While the nation possessed the engineering talent and the factory blueprints required to build a modern air force, it lacked the primary material essential for aircraft construction—aluminum. At the onset of this period, American smelters produced approximately 206,000 short tons of primary aluminum annually, a figure sufficient for civilian needs but woefully inadequate for wartime production.
The demand shock was codified by President Franklin D. Roosevelt’s 1940 mandate for American factories to produce 50,000 military aircraft per year. This goal appeared impossible under existing constraints, as the industry was not equipped for such a massive military buildup. Consequently, the United States government and private sector embarked on an unprecedented industrial expansion. Between 1940 and 1943, new smelters and rolling mills were constructed with federal assistance, and production lines were optimized for 24-hour operation. By 1943, annual aluminum production reached roughly 900,000 short tons, more than quadrupling in less than four years. This historical episode illustrates that when a fundamental material becomes the bottleneck for a national or global priority, the resulting industrial pivot creates a permanent shift in the economic hierarchy.
The Modern Equivalent: Artificial Intelligence and Memory Architecture
In the current decade, a similar phenomenon has emerged within the technology sector. Just as aluminum was the essential, non-negotiable component of 20th-century air power, high-performance memory and processing chips have become the essential components of 21st-century computational power. The catalyst for this modern demand shock is the rapid integration of generative artificial intelligence (AI) across enterprise and consumer platforms.
The infrastructure required to sustain AI models, specifically Large Language Models (LLMs), requires an unprecedented amount of data storage and high-speed retrieval. This has placed companies like Micron Technology Inc. (MU) at the center of a structural supply-demand imbalance. For much of the early 2020s, the memory chip industry was characterized by cyclicality—periods of oversupply followed by price crashes. However, the pivot toward AI data centers has fundamentally altered this cycle, creating a sustained "buy" signal for infrastructure providers.
Quantitative Analysis of the AI Infrastructure Surge
The financial performance of key players in the semiconductor space provides empirical evidence of the current demand shock. Micron Technology’s fiscal reports for 2026 serve as a primary case study for this growth. During the fourth quarter of fiscal year 2026, the company reported earnings that surged 1,078% year-over-year, reaching $37.7 billion, or $32.87 per share. This was a significant leap from the $3.2 billion, or $2.83 per share, reported in the same quarter of the previous year.
Revenue figures followed a similar trajectory, with fourth-quarter revenue soaring 379% year-over-year to $54.23 billion. These figures exceeded Wall Street consensus estimates by significant margins, representing a 5.6% revenue beat and a 5.4% earnings beat. For the full fiscal year 2026, the company reported adjusted earnings of $86.76 billion and total revenue of $133.198 billion. This represents an annual earnings growth rate of 811% and a revenue growth rate of 256.3%. Analysts suggest that these metrics are not merely the result of efficient management, but are the direct consequence of a "demand shock" where the market’s need for High Bandwidth Memory (HBM) and data center storage solutions has outpaced the industry’s ability to supply them.
Chronology of Market Sentiment and Rating Shifts
The transition of the semiconductor industry from a cyclical laggard to a growth leader can be traced through a specific timeline of market ratings and institutional sentiment. Using quantitative grading systems that measure fundamentals such as sales growth, operating margins, and earnings surprises, the shift becomes clear:
- May 2025: Many leading memory providers held low institutional ratings (D-ratings) as the market focused on a perceived glut in consumer electronics and personal computing chips.
- November 2025: As AI data center capital expenditure (CapEx) began to accelerate, quantitative models upgraded these same companies to A-ratings, reflecting improved cash flow and institutional buying pressure.
- January 2026: Leading analysts issued "strong buy" recommendations as the discrepancy between supply and demand became undeniable.
- Late 2026: Financial reports confirmed record-breaking revenue, with stocks in the sector seeing gains in excess of 180% over a 12-month period.
This timeline demonstrates that the "demand shock" was visible in fundamental data months before it was reflected in peak stock prices, mirroring the lead-up to the 1940s industrial expansion.
The Federal Reserve and the 2027 Economic Outlook
As the market looks toward 2027, the role of the Federal Reserve remains a pivotal factor in sustaining or stifling this industrial momentum. Investors are currently weighing "Fed Warning 2027" scenarios, which analyze how monetary policy might impact the capital-intensive nature of the AI buildup. If the Federal Reserve maintains higher interest rates to combat persistent inflation, the cost of financing new chip fabrication plants (fabs) could rise. However, the historical precedent of the 1940s suggests that when a material is deemed "critical," demand often remains inelastic regardless of broader macroeconomic headwinds.
Market analysts are closely watching for signs of institutional "buying pressure" and "earnings surprises" as indicators of which companies will lead the next wave of the 2027 market. The consensus among industrial economists is that the "winners" of the next three years will be those that can successfully scale production to meet the requirements of autonomous systems, advanced robotics, and sovereign AI initiatives.
Broader Implications for Global Supply Chains
The current demand shock has necessitated a re-evaluation of global supply chains. Much like the 1940s necessitated the domestic expansion of aluminum smelting to ensure national security, the 2020s have seen a push for "onshoring" semiconductor production. The U.S. CHIPS and Science Act is a direct response to the realization that silicon is as vital to modern sovereignty as aluminum was to the Allied war effort.
The implications extend beyond the United States. Global powers are currently in a race to secure supply chains for rare earth elements and the high-precision lithography machines required for chip manufacturing. This geopolitical competition ensures that the demand for these technologies will likely remain elevated through 2027 and beyond, as nations seek to build independent technological ecosystems.
Conclusion: Recognizing the Signs of Structural Growth
The primary lesson from the 1940 aluminum shortage is that extraordinary growth does not always require the invention of a new material; rather, it requires a fundamental shift in how an existing material is utilized by the global economy. Aluminum was known for decades before 1940, but it took a global crisis to turn it into a dominant industrial driver. Similarly, memory chips and processors have existed for decades, but the AI revolution has transformed them into the "digital aluminum" of the 21st century.
As 2027 approaches, the focus for investors and policymakers alike is identifying the next "demand shock" winners. These are the companies where demand is accelerating, supply is struggling to keep pace, and earnings are growing at rates that defy traditional cyclical expectations. By focusing on quantitative fundamentals—such as sales growth, earnings momentum, and institutional support—observers can identify the signals of industrial expansion before they become obvious to the broader market. The transition from 2026 to 2027 will likely be defined by those who understand that history does not repeat, but it often rhymes in the way it rewards those who recognize a supply-demand imbalance early.