Data Center Backlash Is Not Killing AI Spending But Changing Where the Money Goes

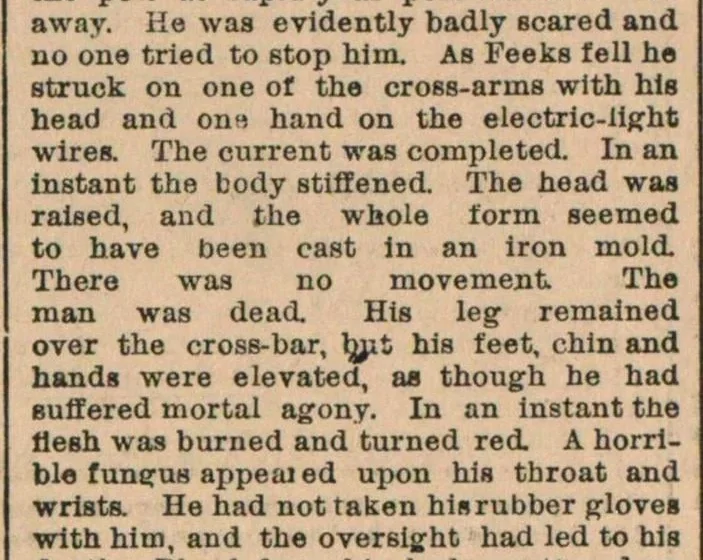
In October 1889, a tragedy in lower Manhattan fundamentally altered the trajectory of American infrastructure. John Feeks, a lineman for Western Union, climbed a 50-foot utility pole to remove defunct telegraph wires. In a grisly scene witnessed by hundreds of onlookers, Feeks came into contact with a live AC line that had been improperly strung alongside low-voltage wires. The resulting electrical surge killed him instantly, leaving his body suspended in a tangle of sparking metal for nearly an hour. The event, widely reported as a "ghastly spectacle," ignited a citywide panic. Building owners began cutting wires from their rooftops, and Mayor Hugh Grant ordered the immediate removal of overhead lines.
The backlash was severe enough that many contemporary observers questioned the future of electricity in urban centers. However, rather than ending the era of electrification, the tragedy accelerated a massive capital shift. Legislation was fast-tracked to force electrical infrastructure underground, a process that was vastly more expensive but ultimately made the grid more resilient, scalable, and publicly acceptable. Today, a similar pattern is emerging in the artificial intelligence sector. While public and legislative resistance to data center expansion is mounting, historical precedents suggest that such friction does not signal the end of the industry’s growth, but rather a pivot in how and where capital is deployed.
The Magnitude of the Modern Data Center Backlash
By the first quarter of 2026, the scale of the resistance against artificial intelligence infrastructure became quantifiable. Estimates suggest that approximately $130 billion worth of U.S. data center projects were either delayed or blocked due to organized local opposition and regulatory hurdles. This movement is not localized to a single region but represents a nationwide shift in public sentiment regarding the physical footprint of the digital economy.
In the summer of 2026, New York became the first state to enact a comprehensive moratorium on new hyperscale data center facilities. The legislation cited concerns over the massive strain these facilities place on the aging electrical grid and the significant volume of water required for cooling systems. Following New York’s lead, over 100 local municipalities across the United States have begun considering similar moratoriums.
The pushback is driven by four primary factors:
- Grid Reliability: Communities express concern that the massive power draw of a single hyperscale facility—often exceeding hundreds of megawatts—could lead to higher utility prices and increased risks of brownouts for residential consumers.
- Resource Scarcity: Data centers require millions of gallons of water daily for evaporative cooling, a significant point of contention in drought-prone regions.
- Noise and Aesthetics: The industrial scale of these "gray boxes" and the constant hum of cooling fans have led to zoning disputes in formerly suburban or rural areas.
- Economic Transparency: Local governments are increasingly questioning the long-term tax incentives granted to data centers, which create relatively few permanent jobs compared to their physical footprint.
Financial Commitments Remain Inelastic Despite Friction
Despite the increasing difficulty of breaking ground on new facilities, the underlying demand for AI compute capacity remains undiminished. Financial disclosures from major industry players indicate that the capital expenditure (CapEx) cycle is locked in for the next decade.
Leaked internal documents from Anthropic’s 2026 initial public offering (IPO) prospectus revealed that the company has secured roughly $518 billion in compute and infrastructure commitments. Critically, approximately 80% of these obligations are noncancelable or "take-or-pay" arrangements, with payment schedules extending into the 2030s. Similarly, OpenAI reported an annualized revenue run rate approaching $70 billion in late 2026, a 70% increase from the start of the third quarter.
The disconnect between public backlash and corporate spending suggests that the industry is entering a "forced evolution" phase. Much like the electric companies of the 1890s that were forced to bury their wires, modern AI firms are being forced to spend more to solve the externalities of their growth. Amazon, for instance, recently committed over $1 billion to community-specific infrastructure funds, aiming to mitigate local concerns through direct investment in public utilities and conservation projects.
A Blue-Collar Resurgence in the AI Supply Chain
As the "easy" sites for data centers are exhausted, the complexity of building new facilities has increased. This shift has rerouted investment toward the specialized firms capable of navigating these technical and regulatory bottlenecks. This transition is fueling a significant blue-collar labor boom, contrasting with the layoffs seen in the software-centric layers of the tech industry.
Labor data from 2026 indicates that experienced electricians in the data center sector now command median salaries exceeding $100,000, while job postings for welders and pipefitters—essential for the liquid cooling systems required by high-density AI chips—have risen by 164% year-over-year.
This industrial demand is reflected in the financial performance of infrastructure firms:
- EMCOR Group Inc. (EME): A leader in mechanical and electrical construction, EMCOR reported record remaining performance obligations of $17.1 billion as of mid-2026, a 44% year-over-year increase.
- Comfort Systems USA Inc. (FIX): Specialized in HVAC and cooling for complex environments, the company posted a $14.1 billion backlog, up 73% from the previous year.
- Quanta Services Inc. (PWR): As a primary contractor for grid modernization, Quanta’s backlog has swelled to over $53 billion, driven by the need to connect remote data centers to high-voltage transmission lines.
The Shift Toward On-Site Power and Distributed Networks
To bypass the limitations of the public electrical grid and avoid the "permitting purgatory" of state-level utility commissions, the data center industry is increasingly turning to on-site power generation. This has created a secondary boom for energy technology companies.
Bloom Energy Corp. (BE) recently surpassed $1 billion in quarterly revenue, a 166% increase attributed largely to the adoption of its solid-oxide fuel cells by data center operators seeking grid-independent power. Caterpillar Inc. (CAT) has also seen a surge in orders for its large-scale industrial generators, which serve as both primary and backup power sources for facilities located in regions where the grid cannot support additional loads.
Furthermore, the industry is moving away from massive, centralized "hyperscale" hubs in favor of distributed cloud networks. Anthropic’s $11.6 billion deal with Akamai Technologies Inc. (AKAM) highlights this trend. By utilizing Akamai’s distributed network of smaller, localized edge nodes, AI providers can reduce the burden on any single power grid while lowering latency for end-users.
The Orbital Frontier: Bypassing Earth’s Constraints
Perhaps the most radical shift in AI spending involves the move toward orbital data centers. If terrestrial land, water, and local opposition become insurmountable barriers, the vacuum of space offers a unique, albeit expensive, alternative.
In late 2026, SpaceX successfully demonstrated the heavy-lift capabilities of its Starship platform, which Elon Musk has stated will be the primary vehicle for launching AI compute satellites. The goal is to establish "significant scale" in orbital compute by 2028. Alphabet Inc. (Google) has also entered this arena, launching experimental AI chips into orbit to test the feasibility of satellite-to-satellite power beaming and thermal management in a vacuum.
Current estimates from financial institutions like Barclays suggest that orbital compute currently costs roughly three times as much as ground-based alternatives. However, as launch costs continue to decline and the regulatory environment on Earth becomes more restrictive, the "space-based compute" model is transitioning from science fiction to a strategic hedge for the world’s largest technology firms.
Strategic Implications for the Future of Infrastructure
The current era of data center backlash mirrors the "War of Currents" in the late 19th century. While Thomas Edison and George Westinghouse fought for market dominance in the headlines, the most consistent wealth was generated by the builders, suppliers, and engineers who physically constructed the modern world.
The AI buildout is following a parallel trajectory. While public attention is focused on the capabilities of chatbots and the controversies of local moratoriums, the capital is increasingly flowing into the "physical layer" of the internet. The companies that provide the specialized labor, on-site energy solutions, and advanced cooling technologies are becoming the primary beneficiaries of the industry’s friction.
As the AI industry matures, the "path of least resistance" for infrastructure is being replaced by the "path of most investment." The backlash is not a signal of decline but a catalyst for a more complex, expensive, and resilient infrastructure phase that will likely define the global economy for the next several decades. Investors and policymakers alike must recognize that the constraints of the physical world—land, power, and public consent—are now the primary drivers of technological evolution.