Financial Analysts Project Potential October Surprise as Historical Market Volatility Patterns Converge Ahead of Midterm Elections

The concept of the October Surprise, a term deeply rooted in American political lore, is increasingly being applied to the financial sector as market analysts observe a rare convergence of technical and fundamental indicators ahead of the upcoming midterm elections. Historically associated with late-breaking political developments that can pivot the trajectory of a national election, the term has found a parallel in Wall Street’s history of significant October shifts. Financial experts Louis Navellier and Marc Chaikin have recently issued warnings regarding a potential "market surprise" that could redefine investor portfolios before voters head to the polls on November 3. Their analysis suggests that the weeks leading up to the election may trigger a substantial realignment of market leadership, a phenomenon supported by historical data dating back nearly a century.
The Political Origin of the October Surprise
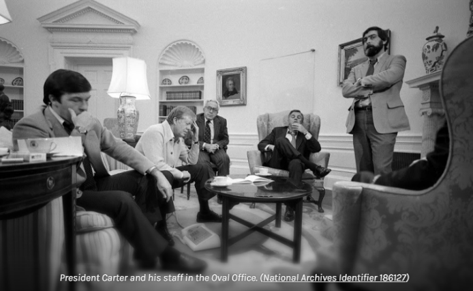
To understand the weight of the term, one must look back to the fall of 1980. For 444 days, the United States was gripped by the Iran Hostage Crisis, during which 52 American citizens were held captive at the U.S. Embassy in Tehran. The crisis became a nightly fixture on American television, most notably through ABC’s Nightline, where host Ted Koppel famously began each broadcast by counting the days of the ordeal. This prolonged geopolitical tension became the central challenge for President Jimmy Carter’s reelection campaign.
In the final months of the race, Ronald Reagan’s campaign manager, William Casey, popularized the phrase "October Surprise." The Reagan camp feared that Carter might secure the release of the hostages just days before the election, providing him with a surge of public support that could secure his second term. While a last-minute deal did not materialize—the hostages were ultimately released on the day of Reagan’s inauguration—the term became a permanent fixture in the political lexicon. It serves as a shorthand for any unexpected, late-season event that catches opposition parties and the public off-guard, fundamentally altering the electoral landscape.
October’s Legacy on Wall Street
While the October Surprise originated in politics, the month has earned a formidable reputation within the financial community. October is often viewed through the lens of the "October Effect," a perceived anomaly where stocks tend to decline or experience extreme volatility. This reputation is anchored by several of the most catastrophic days in market history.
In 1929, the Great Depression was precipitated by the "Black Tuesday" crash on October 29, following a 12.8% drop the previous day. This collapse wiped out billions of dollars in wealth and set the stage for a decade of global economic hardship. Fifty-eight years later, on October 19, 1987, the Dow Jones Industrial Average experienced its largest single-day percentage drop in history, plunging 22.6% in a session now remembered as "Black Monday." More recently, the 2008 financial crisis saw unprecedented volatility throughout October as the global banking system teetered on the edge of collapse following the bankruptcy of Lehman Brothers.
However, historical data suggests that October is not exclusively a month of decline. In many instances, it has functioned as a "bear market killer," marking the end of downturns and the beginning of robust rallies. In October 2022, despite high inflation and rising interest rates, the S&P 500 rose by 8%, the Russell 2000 gained 11%, and the Dow Jones Industrial Average surged 14%. This duality underscores the month’s true characteristic: it is a period of transition and high-velocity direction changes.
A 92% Historical Precedent
The current concern among analysts stems from a specific historical cycle that has shown remarkable consistency since 1925. According to research cited by Navellier, there is a 92% historical precedent for a significant market event occurring in the window immediately preceding a midterm election. This cycle often involves a "shakeout" where the market leadership of the previous three quarters begins to fade, replaced by new sectors that will lead the market into the following year.
Midterm election years are traditionally volatile for the S&P 500. Historically, the index tends to underperform in the first three quarters of a midterm year as uncertainty regarding future policy and congressional control weighs on investor sentiment. However, the period starting in late September or early October often sees the market begin to "price in" the election results. Once the uncertainty is resolved—or as the likely outcome becomes clearer—the market frequently embarks on a year-end rally. The 92% statistic highlights how rarely the market fails to make a decisive move during this specific seasonal window.
The Convergence of Fundamentals and Technicals
The upcoming market shift is being tracked through two distinct analytical lenses: fundamental strength and technical momentum. Louis Navellier, a veteran investor known for his "Stock Grader" system, focuses on quantitative fundamental data. His approach prioritizes companies with high earnings growth, strong sales, and positive cash flow. Conversely, Marc Chaikin, the creator of the "Power Gauge" and a legend in technical analysis, focuses on price action, money flow, and institutional buying patterns.
The collaboration between Navellier and Chaikin is significant because it marks a rare moment where both fundamental and technical systems are signaling the same shift. While Navellier’s system identifies which companies are financially robust, Chaikin’s system identifies when the "big money" on Wall Street—pension funds, hedge funds, and mutual funds—is beginning to move into or out of those stocks.
When both systems align, it suggests that a major sector rotation is underway. Sector rotation occurs when investors move capital from overvalued or slowing industries into sectors poised for growth. In the context of a midterm election, this is often driven by anticipated changes in government spending, tax policy, and regulation. For example, if a shift in congressional power is expected, sectors like defense, healthcare, or energy may see increased institutional interest based on the projected legislative agenda.
Midterm Mayhem: Identifying Winners and Losers
The "Midterm Mayhem" event scheduled for September 29 is designed to address this divergence in the market. Analysts believe that the coming weeks will create a stark divide between "winners" and "losers." This is not a "rising tide lifts all boats" scenario; rather, it is a period of selective growth.
Companies that thrived during the early part of the year—perhaps due to specific economic conditions like high inflation or supply chain disruptions—may face a "reversion to the mean" as the economic cycle matures. Meanwhile, "coiled spring" stocks—those with strong fundamentals that have been overlooked during the year’s volatility—may be the primary beneficiaries of the October shift.
The analysts have indicated that they are monitoring four specific stocks that exemplify this divide. Two of these equities are identified as "must-owns" for the post-election environment, while the other two are flagged as "avoid" or "sell" candidates. This selective approach is crucial in an environment where the broader indices may remain flat or volatile, while individual sectors experience double-digit moves.
Broader Implications and Economic Outlook
The implications of an October market shift extend beyond individual portfolios. Large-scale movements in the equity markets often reflect broader institutional sentiment regarding the health of the U.S. economy. If the anticipated October shift is positive, it could signal that institutional investors believe the Federal Reserve is nearing the end of its rate-hiking cycle or that corporate earnings are proving more resilient than expected.
Furthermore, the relationship between the stock market and election outcomes is well-documented. Historically, if the S&P 500 rises in the three months leading up to an election, the incumbent party has a higher probability of retaining power. If the market falls, it often portends a change in leadership. Therefore, the "October Surprise" in the markets could serve as a leading indicator for the political results on November 3.
As the September 29 briefing approaches, investors are being encouraged to audit their holdings for fundamental strength. The period of "easy money" fueled by broad index growth has largely transitioned into a "stock picker’s market," where granular data and timing are paramount. The combination of historical midterm cycles, the notorious volatility of October, and the current alignment of technical and fundamental indicators suggests that the financial version of the October Surprise may be imminent.
Conclusion: Preparing for the Shift
The convergence of the 1980 political "October Surprise" and modern financial volatility serves as a reminder of the interconnectedness of policy and prosperity. With a 92% historical precedent backing the expectation of a pre-election move, the end of September represents a critical juncture for the investment community.
While the future remains inherently uncertain, the data-driven approach advocated by analysts like Navellier and Chaikin provides a framework for navigating the "Midterm Mayhem." By identifying the sectors that institutional money is beginning to favor and avoiding those with deteriorating fundamentals, investors may be able to position themselves on the right side of the historical cycle. As the calendar turns to October, Wall Street remains on high alert for the next dramatic development that could redefine the economic landscape before the final ballots are cast.