The Evolution of the AI Investment Thesis: Why Cybersecurity Stocks Are Emerging as the Strategic Hedge Against Semiconductor Volatility in 2026

As the global investment community navigates the complexities of the artificial intelligence (AI) era, a fundamental shift in capital allocation is becoming evident. After a two-year period defined by aggressive speculation in semiconductor manufacturers and data center infrastructure, market participants are increasingly seeking "adjacent" opportunities that offer exposure to AI’s growth while mitigating the risks of a potential valuation bubble in the hardware sector. This transition reached a critical inflection point in mid-September 2026, signaling that cybersecurity has moved from a discretionary enterprise expense to a mandatory pillar of the modern digital economy.
The Mid-September Market Rotation
The shift in investor sentiment was punctuated by a significant divergence in trading activity on Monday, September 14, 2026. While the broader technology sector faced headwinds due to fresh warnings regarding AI-related capital expenditure risks, the cybersecurity sub-sector experienced a robust influx of capital. On that day, Nvidia (NVDA) shares declined by nearly 3%, and the VanEck Semiconductor ETF (SMH) fell by 4.4%. Conversely, pure-play cybersecurity firms recorded some of their strongest gains in recent history.
CrowdStrike (CRWD) reached a new record high during the session, while Zscaler (ZS) and SentinelOne (S) posted double-digit percentage increases. This movement suggests that institutional investors are not necessarily retreating from the AI narrative, but rather repricing which sectors will derive the most durable long-term benefits from the technology. As AI enables more sophisticated and autonomous cyber-attacks, the defensive side of the ledger—cybersecurity—is being viewed as a "structural beneficiary" that gains value regardless of whether the AI software boom meets its loftiest expectations.
Market Dynamics and the AI "Double-Edged Sword"
The logic driving this rotation is rooted in the dual-use nature of generative AI. While corporations utilize AI to streamline operations and enhance productivity, threat actors are leveraging the same technologies to launch faster, cheaper, and more scalable attacks. Autonomous malware, AI-driven phishing campaigns, and deepfake-based social engineering have significantly lowered the barrier to entry for cybercrime.
Consequently, cybersecurity has transitioned from a "nice-to-have" budget line item to a critical business continuity requirement. Security vendors are increasingly viewed as "toll-takers" on the AI highway; they are compensated to protect the infrastructure whether the AI applications themselves succeed or fail. This "forced spending" environment provides a defensive floor for the sector that many other software-as-a-service (SaaS) industries currently lack.
Global Spending Projections: 2024–2030
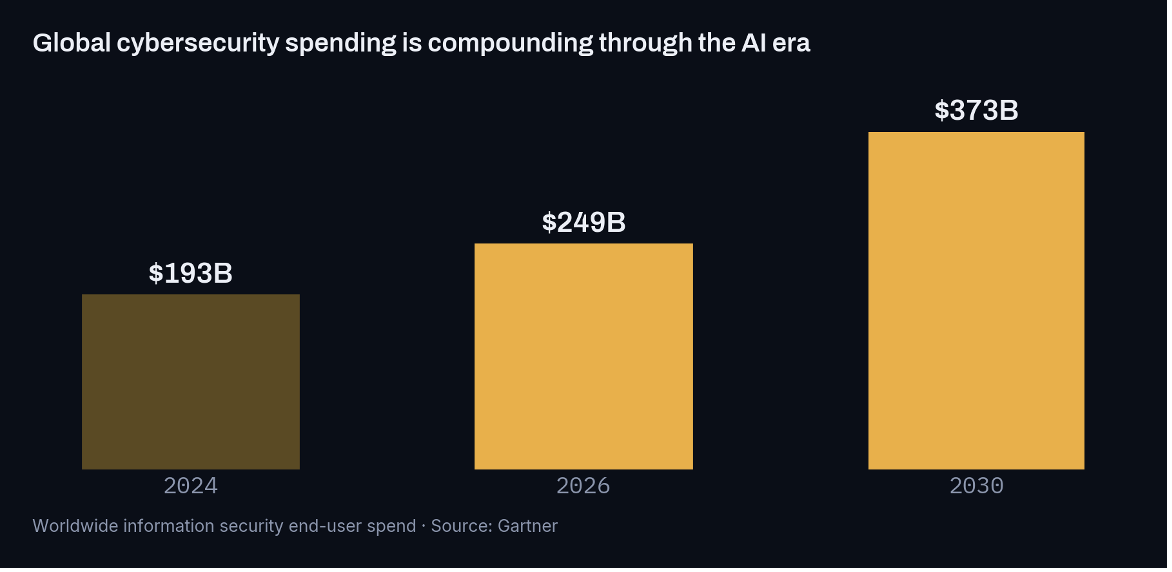
Supporting this investment thesis are revised projections from industry analysts. According to data from Gartner, global information security spending is expected to reach approximately $249 billion in 2026, representing a 13% year-over-year increase. This follows a trajectory that could see the market expand to $373 billion by 2030.
In comparison to 2024, when spending stood at $193 billion, the 2026 figures represent a nearly 30% jump in just two years. This growth is particularly notable given that many enterprise software budgets are currently undergoing consolidation. A recent Morgan Stanley survey of Chief Information Officers (CIOs) revealed that cybersecurity budgets are projected to grow 50% faster than overall software spending.
The most significant growth driver within this sector is the emerging category of "Securing AI." This niche, which involves protecting AI models from data poisoning, prompt injection, and unauthorized access, is projected to overtake traditional endpoint protection as the single largest security spending category by 2029.
Analysis of the 2026 Cybersecurity Leaders
The current market landscape features 15 key players, categorized by their strategic roles within an institutional or retail portfolio. These companies are currently being evaluated based on their ability to integrate AI into their defensive platforms while maintaining high levels of annual recurring revenue (ARR).
The Industry "Generals": Platform Consolidation
The largest players in the space are moving toward a "platformization" strategy, encouraging enterprises to consolidate their disparate security tools into a single, integrated stack.
- CrowdStrike (CRWD): Recognized as the gold standard in endpoint security, CrowdStrike’s Falcon platform has successfully rebranded as "AI security infrastructure." With net new ARR growing over 50% year-over-year and a gross retention rate of approximately 97%, the company remains a top institutional pick despite its premium valuation.
- Palo Alto Networks (PANW): Palo Alto has focused on total platform consolidation. Its acquisition of CyberArk earlier in 2026 has bolstered its identity management capabilities, a crucial area as "AI agents" begin to operate autonomously within corporate networks.
- Fortinet (FTNT): Differentiating itself through proprietary custom silicon, Fortinet remains a leader in the network firewall market. It is often viewed as a value-oriented alternative to its cloud-native peers, offering consistent profitability and steady growth.
- Zscaler (ZS): A pioneer in Zero Trust architecture, Zscaler has pivoted toward securing "agentic AI" traffic. While the stock has faced volatility due to growth guidance adjustments, it continues to trade at a discount relative to other high-growth leaders.
- Microsoft (MSFT): Often overlooked as a pure-play security firm, Microsoft’s security business is now valued at roughly $37 billion. By bundling security into its existing enterprise agreements, Microsoft maintains the most extensive distribution network in the industry.
The High-Growth Disruptors
These companies represent the "torque" in the sector, offering higher potential upside accompanied by increased volatility.
- SentinelOne (S): As a direct challenger to CrowdStrike, SentinelOne utilizes an AI-native architecture (Singularity) that appeals to organizations seeking autonomous threat detection. It remains a frequent subject of acquisition rumors, adding a speculative layer to its valuation.
- Okta (OKTA): Specializing in identity and access management (IAM), Okta is benefiting from the proliferation of AI identities. As machine-to-machine interactions increase, the need for robust identity verification has become a primary security concern.
- Rubrik (RBRK): Focusing on "cyber resilience" rather than just prevention, Rubrik provides solutions for rapid data recovery following ransomware attacks. This "post-breach" focus offers a unique hedge within the security sector.
- Cloudflare (NET): Operating at the intersection of edge computing and security, Cloudflare is uniquely positioned to secure the physical infrastructure of the AI build-out. Its revenue growth remains robust, though it faces competition from both cloud providers and traditional security firms.
Niche and Value-Oriented Players
The remaining segment of the market includes specialized firms that address specific vulnerabilities or provide steady, cash-flow-positive returns.
- Check Point Software (CHKP): Known for its conservative management and high margins, Check Point offers a lower-risk entry point into the sector.
- Varonis (VRNS): Varonis has emerged as a key player in Data Security Posture Management (DSPM). Its tools are essential for companies that are training internal AI models and need to ensure sensitive data is not inadvertently exposed.
- Tenable (TENB) & Qualys (QLYS): These firms lead the vulnerability management space, helping organizations identify and prioritize software flaws before they can be exploited by AI-driven scanning tools.
- Rapid7 (RPD): A smaller-cap player in the security operations (SecOps) space, offering significant leverage on sector-wide recoveries.
- Gen Digital (GEN): Representing the consumer side of the industry (Norton, Avast), Gen Digital provides a dividend-paying, stable alternative to the high-growth enterprise names.
Chronology of the AI Security Supercycle
The current "supercycle" in cybersecurity spending can be traced through three distinct phases:
- Phase 1 (2023–2024): The Hardware Rush. Initial capital was concentrated in Nvidia and infrastructure providers to build the computational power necessary for Large Language Models (LLMs).
- Phase 2 (2025): The Integration Gap. As enterprises integrated AI into their workflows, a surge in "shadow AI" (unauthorized use of AI tools) led to significant data leaks and security breaches.
- Phase 3 (2026–Present): The Defensive Mandate. Organizations recognized that the speed of AI-driven attacks required automated, AI-driven defenses. This led to the prioritization of security budgets over other digital transformation projects.
Broader Impact and Market Implications
The prioritization of cybersecurity has broader implications for the global economy. As cyber-insurance premiums rise and regulatory bodies—such as the SEC and the European Union’s AI Office—tighten disclosure requirements for data breaches, the cost of "doing nothing" has surpassed the cost of high-end security subscriptions.
Institutional analysts suggest that for the remainder of 2026, the key metric to watch will be Net New Annual Recurring Revenue (ARR). This figure serves as a barometer for whether the current market rotation is a temporary reaction to semiconductor volatility or a permanent shift in how the market values AI infrastructure.
Furthermore, the emergence of cybersecurity ETFs, such as the PureFunds ISPY Tech ETF (HACK), the First Trust NASDAQ Cybersecurity ETF (CIBR), and the WisdomTree Cybersecurity Fund (WCBR), has allowed for broader participation in the theme without the risks associated with individual stock selection. These funds have seen record inflows as investors seek a diversified "one-click" exposure to the sector.
In summary, the transition of AI from a productivity tool to a security threat has created a durable, multi-year spending cycle. While the initial "froth" of the AI boom may fluctuate within the semiconductor industry, the companies tasked with defending the digital frontier are seeing their business models validated by both rising threats and expanding enterprise budgets. For the global market, cybersecurity is no longer just a sub-sector of technology; it is the essential insurance policy for the AI age.