The Archie Karas Case Study and the Implementation of Quantitative Metrics to Mitigate Overconfidence in Equity Markets

The narrative of Archie Karas, a Greek immigrant who arrived in Las Vegas in 1992 with $50 and transformed it into a $40 million fortune before losing it all by 1996, serves as one of the most prominent cautionary tales in the history of high-stakes gambling and behavioral finance. While Karas’ journey took place at the poker tables and craps pits of the Mirage, his trajectory illustrates a psychological phenomenon that frequently compromises the performance of professional and retail investors alike: overconfidence bias. In the modern financial landscape, characterized by rapid sector rotations and high volatility, the ability to recognize the transition from skill-based success to chance-based risk is essential for capital preservation.
The Chronology of The Run: Archie Karas and the Illusion of Infallibility
The period between December 1992 and early 1995 is known in gambling circles as "The Run." Archie Karas, formerly a waiter in Los Angeles, began his streak by engaging in high-stakes poker. Over several months, Karas faced and defeated five former World Series of Poker Main Event champions, demonstrating a high level of technical proficiency and psychological resilience. During this phase, his success was largely attributed to skill, edge, and disciplined play.
However, as his bankroll reached the tens of millions, the pool of willing opponents dwindled. To maintain the momentum of his winning streak, Karas transitioned from poker—a game of skill where players compete against one another—to games of pure chance, such as baccarat and craps, where the house maintains a mathematical advantage. By early 1995, Karas had amassed $40 million.
The collapse began in 1995 and concluded in 1996. The same aggressive betting patterns that fueled his rise became the instrument of his downfall when the mathematical variance of the casino games turned against him. Within a year, the entirety of the $40 million fortune was exhausted. Analysts of Karas’ career point to overconfidence as the primary driver of his failure; he believed his "winning hand" was a permanent state rather than a temporary alignment of skill and favorable variance.
The Mechanics of Overconfidence in Financial Markets
In behavioral economics, overconfidence bias is defined as a tendency for an individual to overestimate their own abilities, the accuracy of their information, or their level of control over future events. In the context of the stock market, this psychological trap typically manifests through three distinct behaviors:
- Overestimation of Knowledge: Investors frequently believe they possess superior insight into a company’s future performance compared to the broader market or institutional analysts.
- Illusion of Control: Successful trades during a bull market can lead investors to believe they have mastered market timing, leading to increased risk-taking.
- Miscalibration of Risk: Overconfident investors often ignore "sell" signals, believing that a stock’s previous upward trajectory will continue indefinitely despite deteriorating fundamentals.
These behaviors result in systemic errors, including excessive trading frequency, lack of portfolio diversification, and the tendency to hold losing positions for too long in the hope of a rebound. To combat these biases, market veterans advocate for a shift from qualitative, emotion-driven decision-making to quantitative, evidence-based systems.
Case Study: The Rise and Systematic Exit of Lululemon Athletica (LULU)
The performance of Lululemon Athletica Inc. (LULU) provides a contemporary parallel to the Karas saga, illustrating how disciplined quantitative analysis can protect investors from the risks of emotional attachment to a "winner."
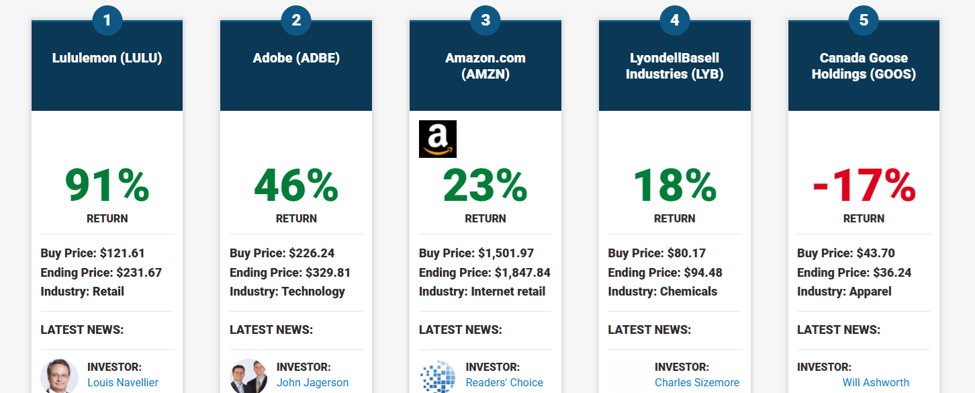
Lululemon emerged as a leader in the athleisure sector, leveraging high-quality product differentiation and a strong brand community to drive consistent earnings growth. In June 2018, quantitative models, specifically those utilizing fundamental and momentum-based grading systems, flagged the stock as a high-conviction "Buy" with an A-rating. This assessment was validated in 2019 when the stock gained 91%, outperforming the vast majority of the S&P 500.
The critical juncture for investors occurred in early 2021. While Lululemon had performed exceptionally well during the initial phases of the COVID-19 pandemic—benefiting from the surge in demand for comfortable home-wear—the quantitative data began to signal a shift. In February 2021, when the stock’s internal rating dropped to a "D," disciplined investors utilized this as a signal to exit, securing gains of approximately 156%.
The Consequences of Holding: 2021–2026
Investors who allowed overconfidence to override quantitative sell signals faced significant capital erosion in the subsequent years. While Lululemon maintained its brand prestige, its financial growth trajectory began to flatten. By 2024, the company’s U.S. comparable store sales growth began to stagnate, leading to a series of downward revisions in management’s guidance.
The erosion of value accelerated in 2025. Following a June 2025 earnings report in which full-year estimates were slashed, the stock plummeted 20% in a single after-hours session. By the end of 2025, the stock had depreciated by approximately 45%. The downward trend persisted into 2026, with shares trading roughly 47% lower year-to-date as of late 2026. Crucially, the stock currently sits 64% below its February 2021 exit point, illustrating the high cost of ignoring data-driven sell signals.
Quantitative Analysis vs. Qualitative Sentiment
The divergence between Lululemon’s stock performance and its perceived brand strength highlights the necessity of "Stock Grading" systems. These systems typically analyze a variety of factors to remove human emotion from the equation:
- Sales Growth and Earnings Momentum: Tracking the rate of change in revenue to identify when a company’s growth phase is peaking.
- Operating Margins: Monitoring whether a company is becoming more or less efficient at generating profit.
- Analyst Upgrades/Downgrades: Assessing the consensus shift among institutional researchers.
- Price Momentum: Identifying when the market’s technical support for a stock begins to break down.
In the case of Lululemon, while the qualitative story remained positive (people still wore the clothes), the quantitative story (slowing store sales and guidance cuts) had turned negative long before the most severe price drops occurred.
Broader Market Implications for 2027
As the financial markets move toward 2027, analysts anticipate a significant "market-moving event" that will likely trigger a massive rotation of capital. This expected shift suggests that the stocks which led the market over the previous five years may not be the leaders of the next cycle.
History shows that market leaders often become the victims of their own success; as valuations become stretched and growth slows, they become vulnerable to significant corrections. Investors who remain overconfident in "legacy winners" risk experiencing a drawdown similar to Archie Karas’ loss of his $40 million fortune.
The upcoming cycle is expected to favor a new group of outperformers, potentially in sectors related to energy infrastructure, advanced manufacturing, or specialized technology applications. Identifying these "next big winners" requires a rigorous adherence to data-driven entry and exit points rather than historical sentiment.
Conclusion: The Necessity of a Disciplined Framework
The Archie Karas story is more than a gambling anecdote; it is a fundamental lesson in the dangers of failing to recognize when a trend has ended. In the stock market, the transition from an A-rated growth stock to a D-rated laggard is often subtle and obscured by the investor’s previous successes.
The data from the Lululemon case study confirms that market timing, when based on quantitative fundamentals rather than intuition, is a vital component of long-term wealth management. As volatility remains a constant factor in global equities, the implementation of systematic grading tools provides a necessary hedge against the inherent human tendency toward overconfidence. For those looking toward 2027, the objective remains the same: identify the evidence, respect the data, and maintain the discipline to sell when the numbers no longer support the narrative. Failure to do so leaves an investor’s fortune to the same whims of chance that eventually claimed the wealth of Archie Karas.